
Ten million dollars, and not one metre drilled
The invoice was close to ten million dollars, and not one metre of hole had been drilled.
That was the number in front of me one evening in a small office where my job was to sit inside other people's oil-and-gas assets and decide which of them were worth backing. Two exploration blocks in West Africa. An operator we knew well. Shallow water sliding out towards true offshore. The purpose of the exercise was not exotic: the operator's producing reservoirs were depleting, and somebody had to find the barrels and cubic metres that would replace them before the decline turned up in the accounts.
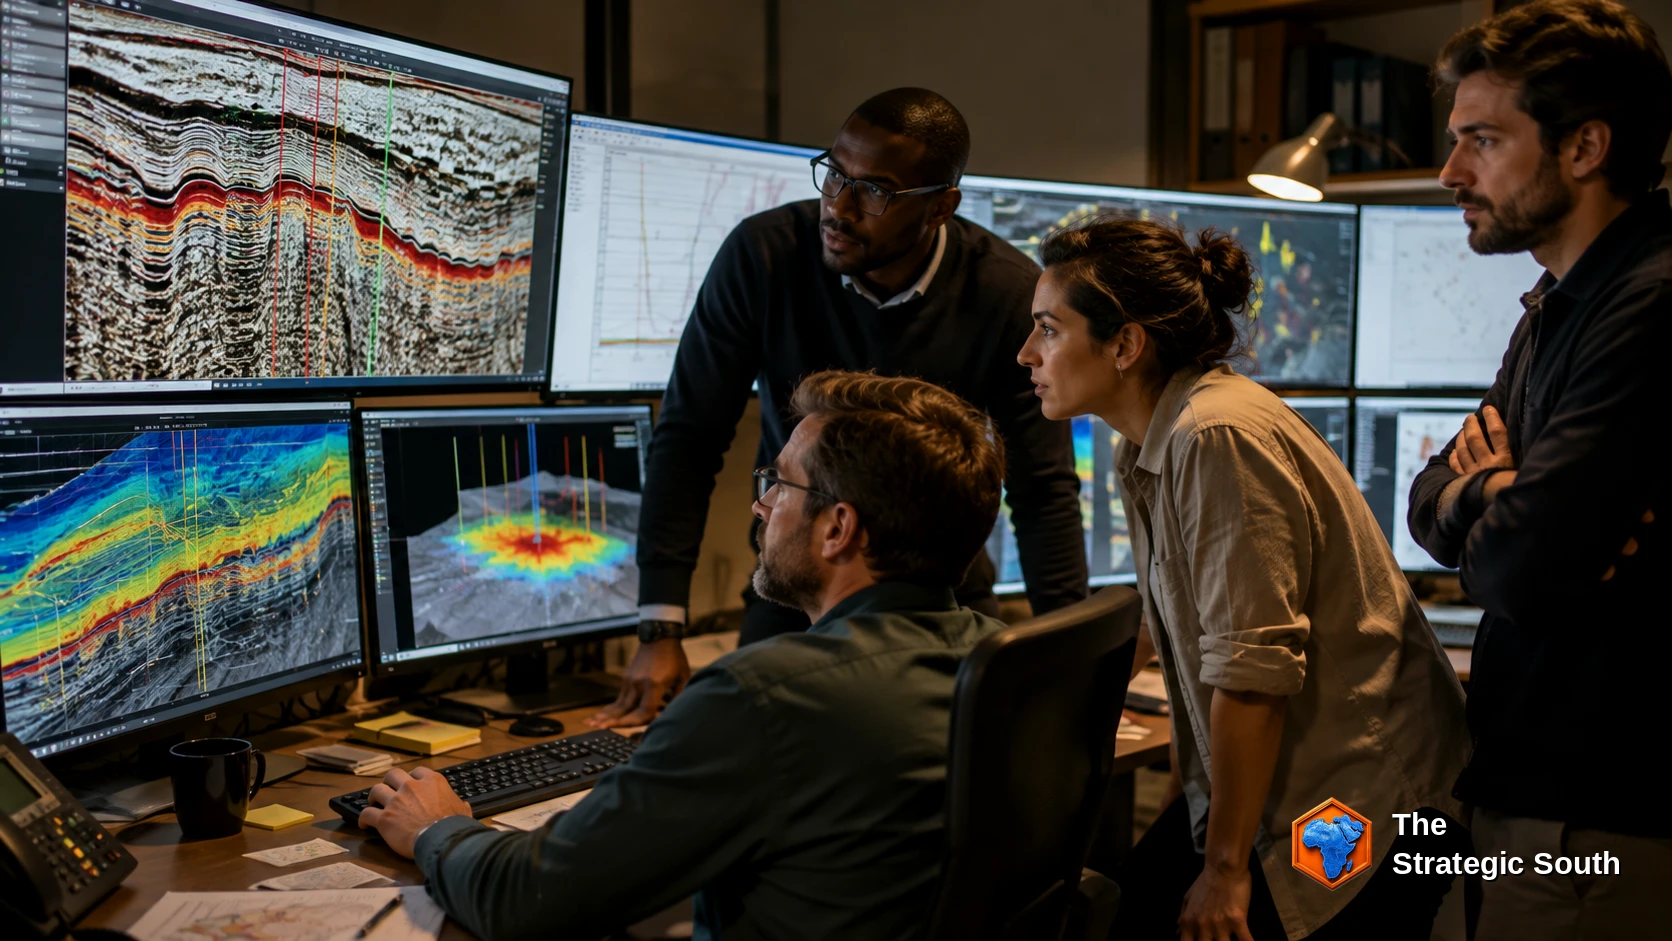
Before anyone spudded anything, we bought the seismic. Then we reprocessed it, because the vintage processing had been done for a different question than the one we were asking. Then came the subsurface studies, in sequence and each with its own contractor and its own months: geophysics, then geology, then reservoir. Close to ten million dollars, and what it bought at the end was two proposed drilling targets and one line of recommendation. Drill here, and here.
Ten million dollars to earn the right to have an opinion.
People flinch at that figure, always, right up to the moment they meet the cost of the alternative. On the buy-side of energy, the expensive mistake is never the study. It is the well you drill, or the cheque you write, without one.
Financial close is the only signature that counts
I spent that stretch on the developer's side of the table rather than the arranger's — holding the money and hunting for somewhere it could safely go, not structuring the debt behind it. From that seat you learn something quickly that no amount of deal news will teach you. A transaction has many signatures, and exactly one of them matters.
A positive analysis is not a deal. A term sheet is not a deal. A memorandum of understanding is not a deal. Two principals photographed shaking hands over a project have moved nothing at all. The only moment that counts is financial close: conditions precedent actually satisfied, guarantees actually lodged, the account actually funded, and capital that can no longer be walked back. Everything before that is intention. Everything after it is delivery.
The entire craft, from where I sat, is closing the distance between an asset that looks financeable in a presentation and one a disciplined investor can genuinely put money behind. Those are rarely the same asset, and being able to tell them apart is the whole of the value I brought to a room.
The price of an informed opinion — and the bigger one of an uninformed one
Ten million dollars buys knowledge. It does not buy certainty, and I insist on that with anyone who thinks a thorough analysis removes risk. It does not remove it. It prices it. You can never buy the outcome; you can only buy a sharper estimate of what you are risking, which is a different thing and a far more useful one.
Those two West African targets were drilled a few years after I moved on, once the operator took the lead. Both were dry.
The hydrocarbon indicator had been textbook-clear — exactly the signal you want, the one you would put in a training deck. It turned out to be residual gas. The reservoir had held hydrocarbons at some point and leaked in geological time, and what remained was a trace clinging to the rock, bright on the screen and worth nothing. Everything on the display said yes. The rock said no.
I have never regarded that as a failure of the work. It is what exploration is. It fails often, and it fails on well-run programmes as readily as on careless ones, which is exactly why the discipline around the money has to be at least as good as the geology inside it. Ten million dollars was the price of an informed opinion. The price of an uninformed one is not on the same scale, and it is paid later, by someone who did not know they had ordered it.
An asset that photographs well and an asset you can actually close are rarely the same asset.
Deals die of attrition, not of rejection
Nobody warns you that most transactions do not die of a no. They die of long-stop dates.
The stretch between a yes on paper and a funded account is a list — a genuinely tedious list — and every item on it belongs to someone who is not in the room when the deal is celebrated. Permits that must be issued rather than promised. Land and access rights registered in a form a lender's counsel will accept. Insurance placed, not quoted. Sponsor equity actually paid in, in cash, rather than pledged in a letter. Accounts opened, security perfected, legal opinions delivered by firms in every jurisdiction the money passes through.
None of that is intellectually interesting and all of it is where the months go. A condition precedent that nobody owns will sit still indefinitely, and the calendar does not care that everything else is ready. That is why the discipline that decides an outcome is so rarely the discipline that got the attention: the deal was not lost in the analysis, it was lost in the nine weeks when a single permit had no named owner.
The other quiet killer is the currency line. An asset earning in one currency and financed in another has its economics rewritten every time the exchange rate moves. You can absolutely close a deal like that. You will rarely keep it healthy. Matching the revenue currency to the debt currency at the start, rather than hedging the gap afterwards, removes a whole category of failure from the closing list — and it is far cheaper to arrange before the term sheet than to repair after it.
A whole company that fit in one room
What I would choose again about that period is its scale. We were about twenty people, seven to ten of us technical, and between us we carried assets worth many multiples of the payroll.
There is nothing like a small team for this work. No committee to shelter inside. No report long enough to bury a doubt in. You look at the rock, you look at the money, and you say what you actually think — in a room small enough that everyone will know, eventually, whether you were right. The arguments were blunt because nobody had the space to posture, and the hours were long because the stakes were real and visible on every desk. Seven people who know a basin cold will outrun a hundred who are waiting to see which way the meeting goes.
That is the texture of the job, and it is the reason I would defend the ten-million-dollar invoice in any room. In a team that size, the study is not a procurement line. It is the whole of what you have to sell.
The Friday I packed up my things
I have kept one ordinary evening as the measure of everything since. Not the invoice, and not the two dry wells.
It was a Friday. A North African gas file I had recommended came back set aside, and I understood — not as an argument but as a fact about the building I was standing in — that the most careful work I was capable of was never going to reach the moment where capital actually moves. Nothing in that house obliged a file to travel any further than the desk it was handed to. In more than two years there, almost nothing I worked on ever reached a funding date.
I remember packing up my things that night and feeling something much closer to grief than to frustration. A good asset had been assembled whole and it was going into a drawer, and the technical work behind it had been real, rigorous, expensive and decorative.
I left because I wanted to be where rigorous work drives the decision rather than decorates it.
What I actually went looking for
I am an operator before I am anything else, and I only really learned that on the money side of the table.
What I miss when I am away from delivery is specific and physical: the weight of a project that has been carried all the way through — guarantees lodged, conditions cleared, the first drawdown landing in an account, and a site waking up the following morning because of it. Nobody applauds the weeks that produce that. They are the weeks between a yes on paper and the day the money can no longer be recalled, and they are the only part of the process that has ever been irreversible.
So I will end on my own account rather than on a rule. I have held the money and I have built with it, and given the choice I know which files I want on my desk now: the ones that survive that unglamorous stretch, with the revenue and the debt in the same currency, the risk priced at its honest number, and every condition precedent carrying someone's name. I would rather spend a career getting a handful of those to the point where the capital genuinely flows than fill a drawer with paper that impressed a room and committed nothing to the ground.
It took exactly one Friday to work out which of those two I could live with.
The Strategic South examines how engineering, infrastructure, energy and industrial systems are reshaping Africa and the Middle East — through the lens of project delivery, not press releases. Subscribe to the weekly newsletter, and explore the companion pieces.